
Food Processing Equipment Market Shifts Toward Smarter, More Integrated Systems
The food processing equipment sector is going through major changes in 2026. Industry events and trade data point to the same direction: buyers want more than standalone machines now.
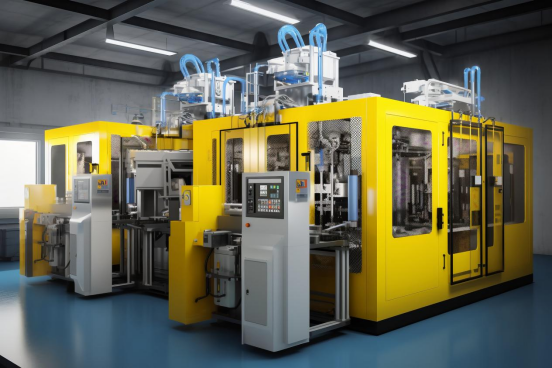
Image Source: 699pic.com
The global market is growing steadily. It was valued at about $66.34 billion in 2026. By 2035, it could reach $110.70 billion, growing at roughly 5.85 percent annually. Asia-Pacific is the largest regional market, accounting for about 45 percent of global demand.
Several trends are reshaping the industry.
At the Shanghai International Food Processing and Packaging Exhibition in June, the shift was visible everywhere. Visual inspection systems for foreign object detection, adaptive packaging controls, robotic palletizing, and intelligent warehouse scheduling were all mainstream offerings. Industry observers noted that the sector has moved from “concept display” to “mature production systems.”
AI-driven visual sorting and automated quality inspection are now standard on many production lines. Robots are being deployed not just for single tasks but for integrated production systems that run with minimal human intervention.
One of the biggest changes is how buyers approach purchases. They are moving away from buying individual machines from different suppliers. They now want integrated production lines that cover everything from raw material handling to finished goods storage.
A buyer from Bangladesh told exhibitors that his factory used to buy machines separately. The result was compatibility problems and long commissioning times. Now he wants one supplier to deliver the whole line. Buyers from Uzbekistan expressed similar views.
Sustainability is no longer optional. European buyers at the Shanghai show said equipment energy consumption and carbon footprint reports are now required for customs clearance. Many Chinese factories are losing orders because they lack green certification.
Under China’s “dual carbon” targets, energy-efficient systems are becoming standard requirements rather than selling points. Heat recovery systems, intelligent temperature controls, and lightweight packaging solutions are all in rising demand.
Chinese food equipment manufacturers are looking overseas. In the first half of 2026, China’s imports and exports with ASEAN reached 4.34 trillion yuan, up 18.2 percent year-on-year. RCEP has made trade easier, with 90 percent of goods now eligible for zero tariffs.
Malaysia has become a key entry point. The country’s food and beverage production grew at 7.2 percent annually from 2015 to 2024. Its strength in halal food certification gives it strategic importance. At MIFB 2026 in Kuala Lumpur, over a dozen Chinese equipment makers exhibited under a unified pavilion.
But challenges remain. Industry experts note that while Chinese equipment is competitive on price, after-sales service is still a weak point compared to European and Japanese competitors. Customers want fast local service, not just competitive prices.
The industry is also seeing new entrants. Ningbo Junpu Intelligent Manufacturing, previously focused on automotive and industrial automation, won its first food industry order in early 2026. The company is building bread roll loading systems for a German food company. The equipment handles hundreds of products per minute with food-grade materials and IP65 protection.
Meanwhile, established players are upgrading. Hangzhou Yongchuang Intelligent Equipment is developing humanoid robots for packaging applications. Hangzhou Zhongya Machinery has broken foreign dominance in aseptic filling equipment, now serving companies like Yili and Mengniu.
The food processing equipment market is entering a new phase. AI, robotics, whole-line integration, sustainability, and globalization are the key forces driving change. Companies that can deliver integrated solutions with strong after-sales support will lead the next wave of growth.